The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Refinance eligibility depends on more than finding a lower advertised rate. Australian lenders commonly assess income, expenses, credit history, home equity, LVR, property valuation and supporting documents before deciding whether to approve a refinance application.
Home loan refinance eligibility in Australia depends on how a lender assesses your overall borrowing position, not just whether you already have a mortgage. When you refinance, you are usually applying for a new loan to replace your existing one, so the new lender will review your income, expenses, debts, credit history, property value and the purpose of the refinance.
This article explains the main mortgage refinance requirements Australian borrowers may encounter. It is general information only and does not take your personal objectives, financial situation or needs into account. Eligibility, rates, fees and loan features vary by lender and depend on individual circumstances.
What does refinance eligibility mean?
Refinance eligibility is the lender’s assessment of whether you may be able to take out a new home loan and meet the required repayments. A lender may consider whether the loan amount is appropriate for the property, whether you can service the repayments, and whether your application fits its credit policy.
Being eligible with one lender does not automatically mean you will be eligible with another. Lenders can differ in how they treat income types, employment history, living expenses, existing debts, property locations, loan-to-value ratios and credit issues.
The main factors lenders assess
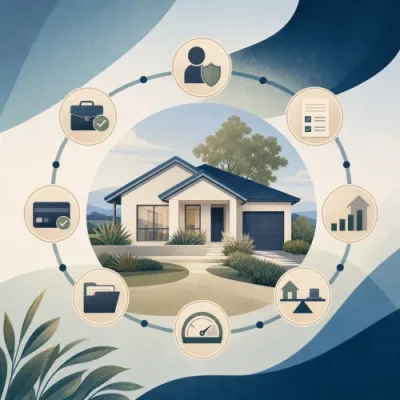
While each lender has its own criteria, most refinance assessments include a similar set of checks. The table below summarises the major factors and why they matter.
| Eligibility factor |
Why it matters |
| Income and employment |
Helps the lender assess whether your income is stable and sufficient to support repayments. |
| Expenses and debts |
Shows how much of your income is already committed to living costs, loans, credit cards and other obligations. |
| Equity and LVR |
Indicates how much of the property you own compared with the amount you want to borrow. |
| Credit history |
Gives the lender information about repayment conduct, defaults, credit enquiries and existing credit accounts. |
| Property valuation |
Confirms the lender’s view of the property’s value and suitability as security for the loan. |
| Loan purpose |
Explains why you want to refinance, such as changing loan features, consolidating debts or accessing equity. |
| Documents |
Supports the information in your application and helps the lender verify your financial position. |
Income, employment and serviceability
Serviceability is the lender’s assessment of your ability to meet repayments on the new loan. It usually involves looking at your income, regular expenses, existing debts and potential repayment obligations under the proposed loan.
Common income sources may include salary, wages, self-employed income, rental income, overtime, bonuses, commissions, government payments or other regular income. Not all lenders treat these income types the same way. Some may require a longer history for variable income, while others may discount certain income sources or ask for additional evidence.
Lenders also consider employment stability. A borrower who has recently changed jobs, moved from permanent employment to contracting, or started a business may need to provide more supporting information. This does not necessarily mean refinancing is unavailable, but it may affect which lenders are willing to assess the application and what documents are required.
Expenses, debts and repayment history
Your expenses and existing debts may have an effect on mortgage eligibility in Australia. Lenders may review everyday living costs, dependants, credit card limits, personal loans, car loans, buy now pay later accounts, tax debts, HECS or HELP debts, and other ongoing commitments.
Credit card limits may matter even if you pay the balance in full, because lenders may assess the available limit as a potential liability. Similarly, personal loans or car finance can reduce borrowing capacity because they create fixed repayment obligations.
Your current home loan repayment conduct is also important. Missed or late repayments may raise questions, especially if they are recent or repeated. If there is a clear explanation, it may be worth discussing it before applying rather than waiting for the lender to identify the issue during assessment.
Equity, property value and refinance LVR
Equity is the difference between the value of your property and the amount you owe on it. For example, if a property is valued at more than the outstanding loan, the difference is your equity. A refinance with equity may provide more lender options, depending on your income, debts and the lender’s policy.
Loan-to-value ratio, or LVR, compares the loan amount with the lender’s assessed property value. A lower refinance LVR generally means there is more equity in the property, which may improve the range of options available. A higher LVR can limit lender choice, affect pricing, or result in additional requirements such as lenders mortgage insurance, depending on the lender and loan structure.
The lender’s valuation is important because it may not match your own estimate or a recent sales appraisal. If the valuation comes in lower than expected, your LVR may be higher than planned. This can affect the loan amount available, the ability to access equity, or whether the refinance still makes financial sense after costs are considered.
Credit history and credit score
Your credit history helps lenders understand how you have managed credit in the past. It may include repayment history, credit enquiries, existing credit accounts, defaults, bankruptcies, court judgments or hardship arrangements.
A clean credit history can support an application, but it is not the only factor. Likewise, a past credit issue does not automatically rule out refinancing, although it may reduce lender choice or lead to stricter assessment. The timing, severity, explanation and whether the issue has been resolved can all matter.
Before refinancing, it may be useful to check your credit report for errors or unfamiliar enquiries. If something is incorrect, addressing it before applying may reduce delays. Avoid making multiple home loan applications at once without understanding how enquiries may appear on your credit file.
Loan purpose and refinance structure
Lenders may ask why you want to refinance. Common reasons include seeking a different rate type, changing loan features, consolidating debts, accessing equity, switching lenders, changing from interest-only to principal and interest, or restructuring investment and owner-occupier lending.
The purpose can affect assessment. For example, refinancing to consolidate unsecured debts may involve different checks from refinancing simply to change lenders. Accessing equity for renovations, investment or other purposes may require evidence of how the funds will be used. Investment lending may also be assessed differently from owner-occupier lending.
It is important to consider the total impact of the refinance, not just the new repayment. Extending the loan term may reduce repayments in the short term but can increase the total interest paid over time. Debt consolidation may simplify repayments, but converting short-term debts into a long-term home loan can increase long-term costs if not managed carefully.
Refinance application documents commonly requested
The exact refinance application documents depend on your employment type, lender and loan purpose. However, borrowers are commonly asked to provide evidence that supports their identity, income, expenses, existing loan and property details.
- Identification: documents that verify your identity.
- Income evidence: recent payslips, employment details, tax returns, business financials, rental statements or other income records.
- Existing home loan information: recent loan statements showing repayments, balance and account conduct.
- Bank statements: transaction or savings account statements that show income, expenses and account management.
- Rates or property details: information that helps identify the property being used as security.
- Liability details: statements for credit cards, personal loans, car loans or other debts.
- Purpose evidence: invoices, quotes, debt statements or other documents if you are accessing equity or consolidating debts.
A mortgage broker or lender may request additional documents after reviewing your situation. You can also review mortgage broker support if you want help understanding documentation and lender policy differences.
How special circumstances may affect eligibility
Some borrowers have circumstances that require a more detailed assessment. This does not necessarily prevent refinancing, but it may make lender selection and preparation more important.
Self-employed borrowers
Self-employed borrowers may need to show business income over a longer period and provide tax returns, financial statements or accountant-prepared information. Lenders may look at business consistency, income trends, debts, expenses and the structure of the business.
Borrowers accessing equity
If you want to refinance with equity, the lender will consider the property valuation, your LVR, your purpose for the funds and your ability to service the higher loan amount. Accessing equity increases your debt, so the lender may assess the proposed loan more closely than a simple lender switch.
Borrowers with recent credit issues
Recent missed repayments, defaults or hardship arrangements may affect eligibility. Some lenders may require issues to be resolved or may apply stricter conditions. It may help to gather explanations and evidence before applying.
Investors
Investment property borrowers may need to provide rental income evidence, tenancy details, expense information and details of other loans. Lenders may apply different policies to investment loans and may assess rental income conservatively.
Costs and timing can also affect whether refinancing is worthwhile
Eligibility is only one part of the refinance decision. Even if you may qualify, the refinance still needs to make sense after costs, risks and loan terms are considered. Potential costs may include discharge fees, application fees, valuation fees, settlement fees, government charges, break costs on fixed loans and lenders mortgage insurance where applicable.
Timing can also matter. If your fixed-rate period is ending, your income has changed, your property value has shifted or you are planning to move soon, the overall benefit of refinancing may differ. A repayment estimate can help you compare scenarios, and the site’s home loan calculators may be a useful starting point for modelling repayments or borrowing assumptions.
How to prepare before applying to refinance
Preparation can reduce delays and help you understand your position before a lender reviews the application. Consider the following steps:
- Review your current loan: check your balance, rate type, repayment amount, fees and any fixed-rate conditions.
- Estimate your property value: use recent comparable sales and remember that the lender’s valuation may differ.
- Check your debts: list credit cards, personal loans, car finance and other commitments.
- Review your budget: understand your regular expenses and whether repayments would remain manageable if circumstances changed.
- Gather documents early: missing statements or income evidence can slow assessment.
- Avoid unnecessary new credit: new debts or multiple enquiries may affect borrowing capacity and credit assessment.
- Compare the full loan structure: consider fees, features, repayment flexibility and total cost, not only the advertised rate.
Key questions to consider before refinancing
Before lodging an application, it may help to ask:
- Do I have enough equity for the loan amount I want?
- Has my income changed since I took out my current loan?
- Are my expenses and debts likely to reduce my borrowing capacity?
- Is my repayment history strong over recent months?
- Will I need to pay break costs, discharge fees or lenders mortgage insurance?
- Am I refinancing for a clear purpose, and have I considered the long-term cost?
- Which documents will the lender need for my employment type and loan purpose?
The bottom line
Home loan refinance eligibility in Australia is based on a combination of serviceability, income stability, expenses, debts, credit history, equity, refinance LVR, property valuation, loan purpose and supporting documents. No single factor guarantees approval, and different lenders may reach different outcomes.
If you are considering refinancing, start by understanding your current loan, checking your equity position and gathering your documents. From there, comparing lender requirements and repayment scenarios can help you decide whether a refinance application is worth exploring.
Published: Thursday, 22nd Oct 2026
Author: Paige Estritori


No comments yet. Be the first to share your thoughts.